TIER & Now

Q3 2026 Edition
Explore how TIER Wealth is contributing to today’s conversations in the financial world.
Tax
Give to Charity, Not to CRA: Year-End Giving Strategies That Pay Off
As the calendar turns to October and year-end approaches, it is time to start thinking about tax planning. Many taxable investors have seen solid gains over the last few years. We thought it would be worthwhile to highlight a few charitable giving strategies that can be used to help with tax planning, both during your lifetime and for your estate:

1. Donate Appreciated Securities In-Kind

Giving publicly listed investments like mutual funds, ETFs or individual shares directly to a registered charity means no capital gains tax on the growth, and you still get a donation receipt for the full market value at the time of donation. Compared with selling the shares first and donating the after-tax cash, both you and the charity come out ahead.

2. Give More in High Income Years

You can typically claim the donation tax credit up to 75% of your net income. Therefore, the higher your income , the more of a large gift you may be able to claim. If you are planning a large gift, it is best to time it with a high-income year when possible.

3. Donate Through Your Corporation

If you hold eligible appreciated publicly traded securities in a private corporation, they can be donated with no capital gains tax, and the corporation can claim a deduction. The full gain is then added to the capital dividend account, increasing the amount shareholders can withdraw from the corporation tax free.

4. Name Charities as Beneficiaries on Taxable Registered Accounts

You can name a charity as a full or partial beneficiary of your taxable registered investment accounts (RRSP/RRIF). The gift then passes outside of your estate, avoiding probate fees and keeping it out of the public record. The donation credit can offset up to 100% of your net income in the year of death, so this strategy helps soften the tax bill that can come if you pass away with large registered account balances.

5. Consider Establishing a Donor Advised Fund

Establishing a donor advised fund (DAF) can allow you to give a large donation of cash or securities in the current year for tax purposes and then spread the grants out to your favorite charities over time. This gives you many of the benefits of a private foundation without the associated cost and paperwork and can be a great way to involve the whole family in the giving process.

A Word on Alternative Minimum Tax

Under the normal tax rules, a capital gain on donated securities is fully excluded from tax, and the donation credit fully recognized. However, under the recently changed Alternative Minimum Tax (AMT) rules, 30% of the capital gain on donated securities is included in adjusted taxable income to determine if AMT will apply, and only 80% of the regular charitable donation tax credit is recognized in the same calculation.

For most donors, this is less concerning than it may sound. A donation that can be fully claimed in the year cannot, on its own, trigger federal AMT — even where the donated securities are highly appreciated. AMT can however become relevant where a large donation is combined with other items such as significant realized capital gains, or where an in-kind gift of appreciated securities is large enough that the full donation cannot be claimed in the year it is made.

If you are considering a significant gift, we are happy to model the tax and AMT consequences in advance, including the impact of the province in which you live. If AMT has already been triggered, we can also assess how much is likely to be recovered over the seven-year carryforward period and whether any planning opportunities remain.
Investment
Why Bond Yields Matter
Yields Are Back In The Headlines

The 10-year US Treasury yield is back above 5%, and it has become one of the most-watched numbers in finance this quarter. On September 23, it closed at 5.11%, its highest close since July 2007. For context, it closed at 3.96% on February 27, the day before the conflict with Iran began.

Bond yields can feel abstract, but they sit underneath almost every financial decision: what a mortgage costs, what a company is worth, and what a government pays to borrow. Below, we explain why this move matters, what is driving it, and how Q Wealth Partners is positioning client portfolios.

Is 5% Actually High?

By long-run standards, not really. Since the 1980s, the 10-year Treasury yield has averaged roughly 5.5% to 5.7%. That average is pulled up by the 1980s and 1990s, when inflation and interest rates were far higher; the yield peaked above 15% in 1981.

What has changed is how much everyone owes. Governments, companies and households now carry far more debt than they did in the 1980s. When debt is this large, each rate increase bites harder, slowing spending and raising the risk that something breaks. That sensitivity may act as a ceiling on how high rates can go before policymakers, or the economy itself, push back.

What Bond Investors Are Telling Us

A bond yield is the market's collective verdict on the economy. When investors lend to a government for ten years, the yield they demand reflects where they expect short-term interest rates to go, how much inflation they expect to impact their return, and the premium for tying up money for a decade.

All of these factors are helping keep bond yields higher. Inflation remains above target, the economy has been more resilient than expected, and governments and corporations continue to issue large amounts of debt. With U.S. government debt now exceeding $40 trillion, some investors are demanding higher yields to compensate for increased borrowing and fiscal uncertainty.

Why Stock Investors Should Care

Rising bond yields can influence stock prices even when the outlook for corporate earnings remains positive. One reason is that higher yields raise the discount rate investors use to value future earnings, reducing the present value of those profits. This effect is particularly noticeable for growth companies, whose expected earnings are concentrated further into the future.

Higher yields also make bonds a more compelling investment alternative. As returns on government bonds increase, investors may require a greater return from equities to justify taking on additional risk. When that gap narrows, some capital naturally shifts from stocks to fixed-income investments.

At the same time, higher interest rates can affect companies directly. Businesses that need to refinance debt or take on new borrowing may face higher financing costs, which can weigh on profit margins and leave less room for capital investments, acquisitions, share buybacks, or dividend growth.

Rising yields also create a headwind for existing bondholders. Because bond prices move inversely to yields, increases in market interest rates can cause the value of currently held bonds to decline, particularly those with longer maturities. While investors continue to receive their contracted interest payments, higher rates can drive short-term price volatility in fixed-income portfolios.

The Squeeze On Consumers

Bond yields influence many borrowing rates, so when yields rise, consumers often feel the impact through higher mortgage rates, car loans, and other forms of credit. In the US, the 30-year fixed mortgage rate has risen above 7%, raising borrowing costs and pressuring household budgets.

Because consumer spending drives roughly two-thirds of US economic activity, higher interest payments can leave less room for discretionary spending. If this trend persists, it could weigh on economic growth. Canadians renewing mortgages over the next year may face similar challenges as they adjust to higher borrowing costs.

Not everyone is negatively affected, however. Higher yields mean savers are finally earning more on cash, GICs, and other money-market investments, making them a more attractive component of a diversified portfolio.

How We Are Navigating It

Rising yields and uncertainty around inflation, interest rates, and energy markets are likely to keep volatility elevated. Q Wealth Partners’ portfolios are designed with this in mind. Rather than relying on a single type of bond, Q Wealth’s portfolio managers maintain exposure to a range of sectors, maturities, and regions that can perform differently as market conditions change.

The goal is not to predict one outcome, but to build a diversified fixed income portfolio that can help manage risk across different environments.

There is also a silver lining. Higher yields mean that newly purchased bonds offer significantly more income than they did just a few years ago. That higher income provides a greater cushion against market fluctuations and can support stronger long-term returns.

If you have any questions about how these developments may affect your portfolio, please don't hesitate to contact us.
Provided by:
Yaw Boadu
Portfolio Manager, Quintessence Wealth
"Q Wealth Partners" text logo
Estate & Insurance
The Best Gift You Can Give Your Executor: A Plan They Don't Have to Guess At
Most people think of estate planning as a single event - the day you sign your will. In reality, a will is only the skeleton. The muscle and connective tissue of a good estate plan is everything around it: the documents that are current, the beneficiaries that are correctly named, the passwords someone can actually find, and the wishes you've written down instead of assumed your family already knows.

That distinction matters more than most people realize, because the person who inherits the gap between "I have a will" and "I have a plan" is not you. It's your executor - very often a spouse, sibling, or adult child who is grieving at the exact moment they're asked to become a project manager, forensic accountant, and family referee all at once. The single greatest gift you can give that person isn't a bigger inheritance (although that is nice too!) -it's specificity.  An estate plan that is simplified, documented, and precise removes guesswork at the one moment in their life when they have the least capacity to guess well.

Consider what an executor actually has to do: locate original documents, identify every account and asset, confirm who's named where, settle debts, communicate your wishes to family members who may not agree with each other, and do all of this under legal deadlines - often without even knowing where to start. Every undocumented detail becomes a delay, a legal cost, or a family disagreement. Every documented one becomes a decision your executor doesn't have to make alone.  Imagine the relief your executor would feel if they discovered you had pre-planned or even pre-paid your entire end of life arrangements for them, and there were no decisions to make at all!

This is why we built the Estate Readiness Checklist, and why we have been introducing it with clients at every annual review. It isn't a legal document - it's a diagnostic. It breaks estate readiness into six areas where gaps most commonly hide:
  • Legal Documents - is your Will current and signed, do you have Powers of Attorney and a Personal Directive in place, and are alternates named in case a primary executor or attorney can't act?
  • Insurance - has coverage actually been reviewed against your current life, not your life from ten years ago? Are the beneficiaries current or is your ex-spouse still named?
  • Beneficiary Designations - do your RRSP, TFSA, LIRA, and pension elections still reflect what you want, and do you and your executor know the difference between a named beneficiary and a successor holder?
  • Financial Organization - could someone else reconstruct your full financial picture from what you've left behind, including digital accounts and passwords?
  • Final Wishes - have you actually told your family what you want, rather than trusting them to guess correctly under pressure?
  • Essential Contacts — does your executor know who your financial advisor, lawyer, accountant, and other advisors are, and how to reach them?  Do they have to go through boxes of stuff in the basement to find your estate documents or do they know exactly where everything is kept?
Each item on the checklist is weighted by real consequence - critical items are the ones that create genuine legal or financial exposure if they're missing, while others simply add polish to an already solid plan. The goal isn't a perfect score. It's an honest one, revisited each year, so you can identify weak spots over time instead of your executor discovering them the hard way.

What we see most often isn't a client who has done nothing - it's a client who has done most of it, years ago, and never returned to update it.  A will written before a divorce.  A beneficiary form that still names a sibling instead of a spouse.  A “letter of wishes” that exists only as a conversation nobody wrote down. These aren't failures of intention. They're simply what happens when planning is treated as a one-time task instead of an ongoing habit.

Simplifying, documenting, and being specific now costs you an afternoon or an evening of your time.  Leaving it undone costs your executor weeks of uncertainty, and can even sometimes cost your family a relationship. If it's been a while since you've looked at your own plan through this lens, that's exactly what the checklist is for! If you haven’t seen it yet, be sure to reach out to your advisor to ask for an electronic copy, or we can work through it together at our next Annual Review.
Random
News and Updates from TIER Wealth
TIER Gets a Little Bigger!

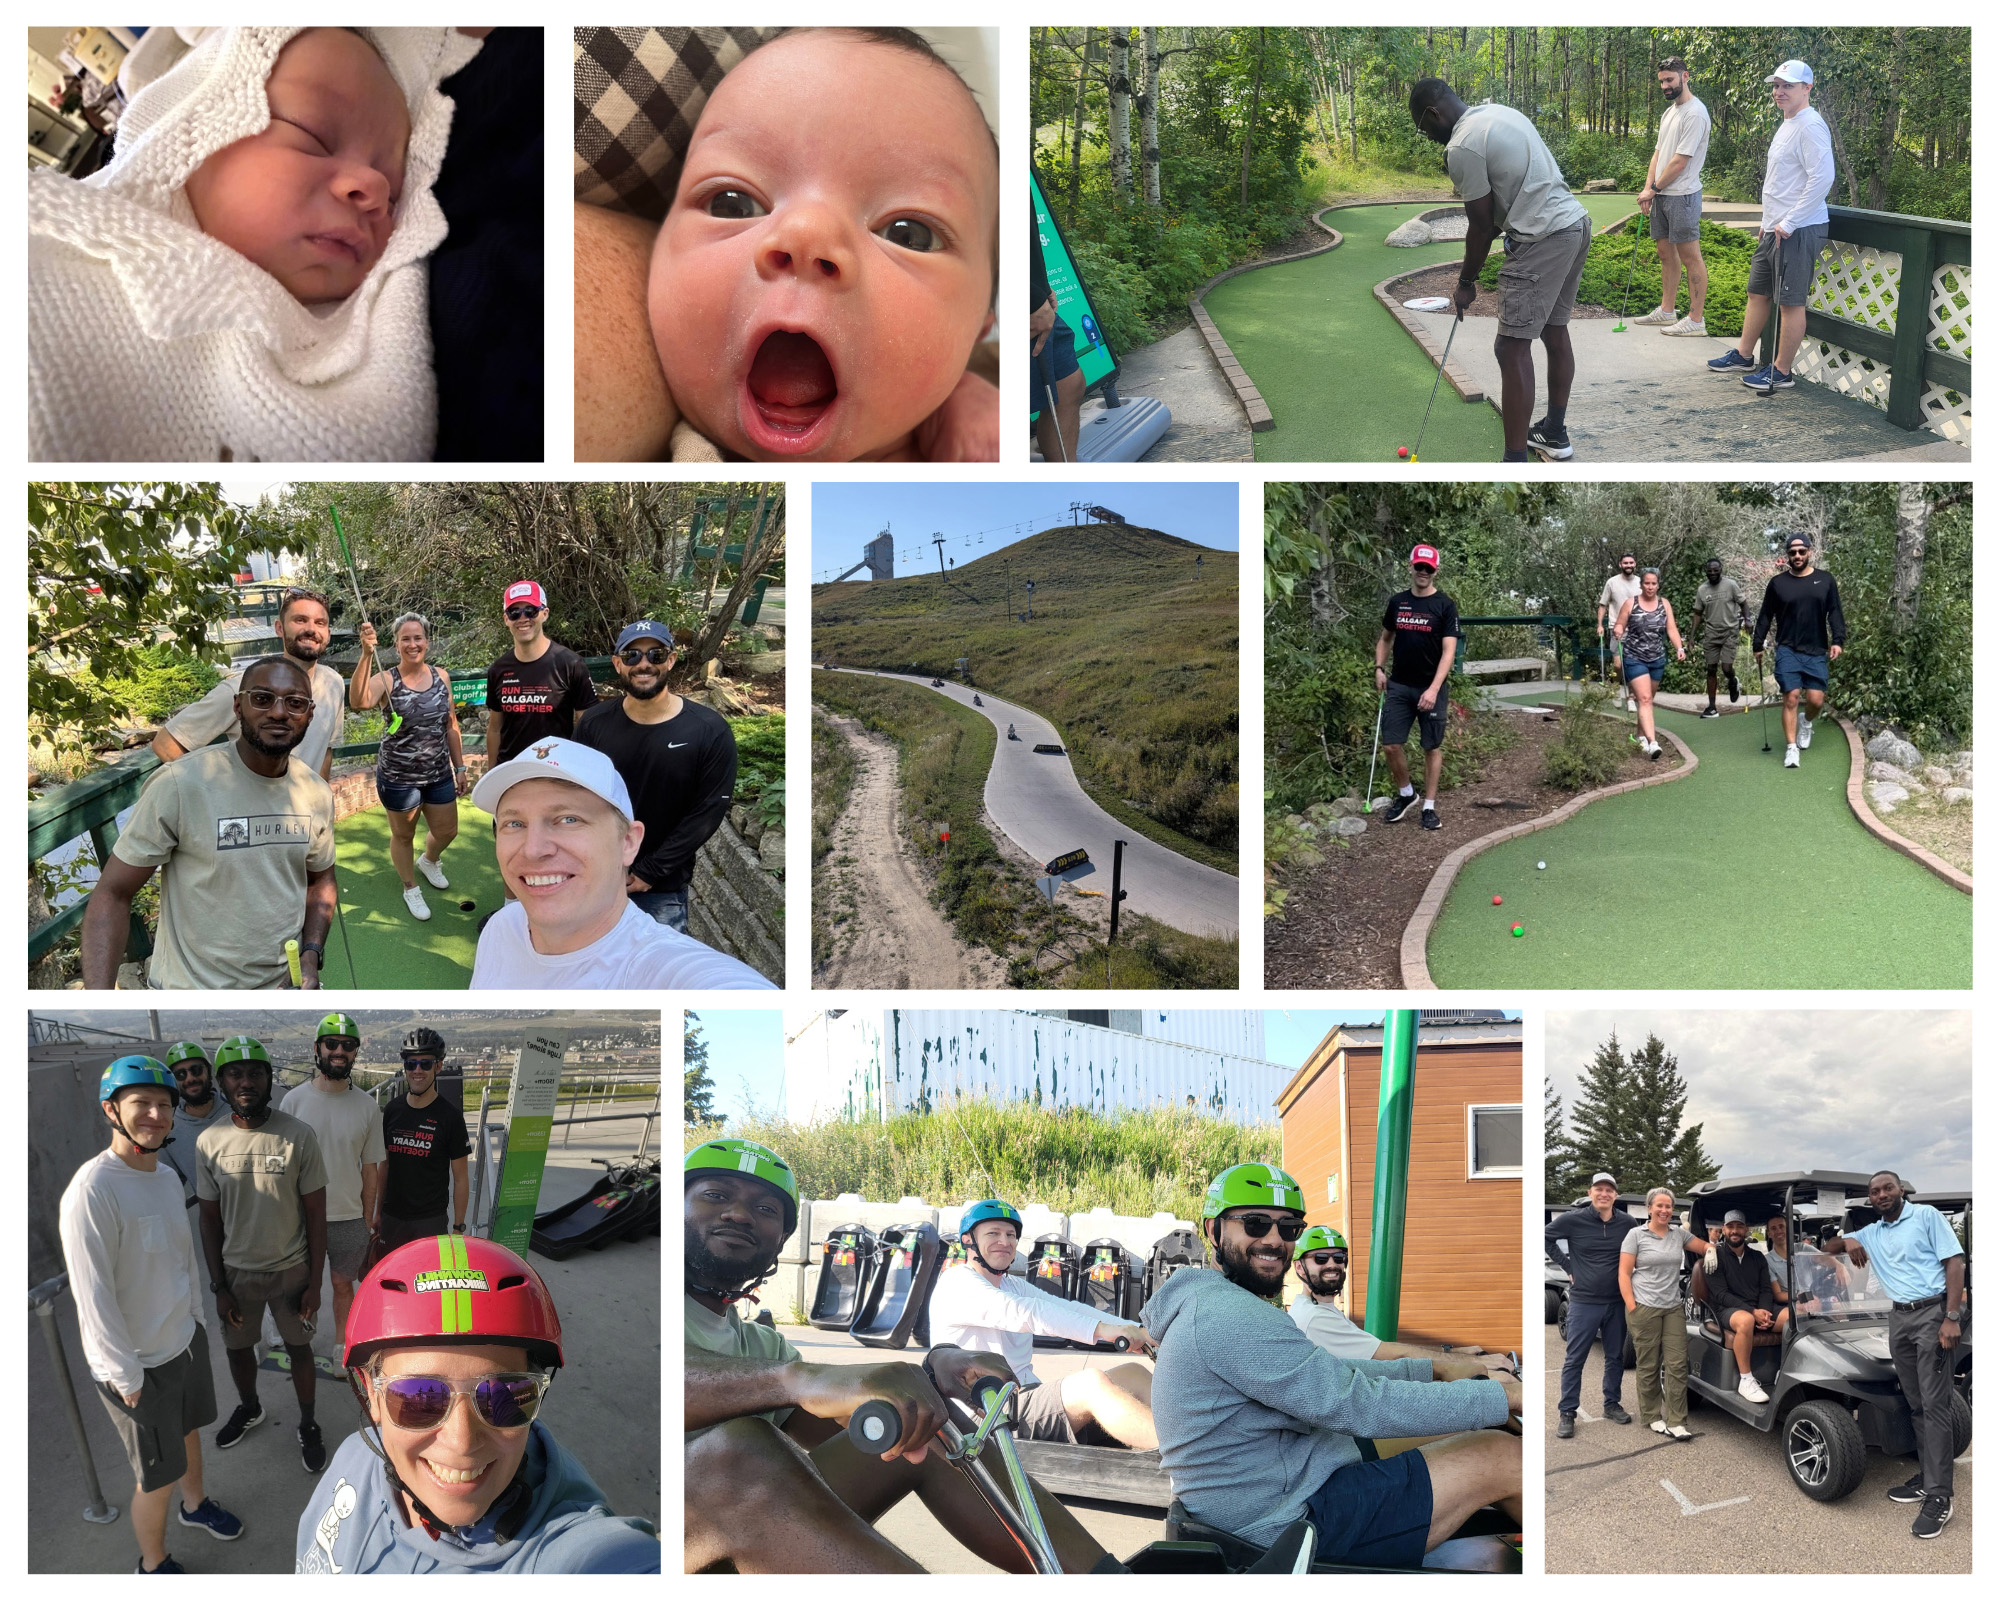
Associate Wealth Advisor Jordan Dawit and his wife Kelsey welcomed their daughter, Harper Marin Lyn Dawit on Saturday July 25 at 2:36pm, weighing in at a healthy 6 lbs 13 oz and measuring just shy of 20 inches long. As first timers, Jordan and Kelsey are sleep deprived but excited for this new chapter in their lives.  Congratulations Jordan and Kelsey!

Downhill Thrills, Uphill Skills

The TIER team had their second team building day on August 28th, where we headed to Canada Olympic Park for downhill karting and mini golf.  Despite some near misses on the race track and the highest putting score (Jen) having to buy ice cream for the rest of the team, lots of fun was had at our Q3 TIER Wealth Team Day!

Fore Families

‍
The TIER team participated in Canvas Wealth’s Fore Families Annual Charity Golf Tournament on September 2nd, which supported the local charity Made by Momma.  Over $10,000 was raised for this completely volunteer-run Calgary based charity that supports mothers and young children going through hardships, and TIER was ecstatic to be a part of it!

‍Deep Dives in Planning Topics
In last quarter’s TIER & NOW newsletter, we introduced our new article series “RANDOM”, which takes a deep-dive into more technical topics.  Rather than AMT as originally planned, our first issue covered the optimal funding of RESP (Registered Education Savings Plan) accounts and is available on our website here: tierwealth.com/random ; and was also featured in the Globe and Mail.
The information contained in this newsletter comes from sources we believe to be reliable, but we cannot guarantee its accuracy or reliability. The opinions expressed are based on analysis and interpretation as of the date of publication and are subject to change without notice. The information may not apply to all readers. The views expressed in this newsletter are those of the author and do not necessarily reflect the opinion of TIER Wealth as a firm.
Stay connected.
Subscribe to our newsletter.
Thank you! Your submission has been received!

Schedule Your
Discovery Meeting

Fill out the form below to begin discussing how we can help you.
*(Scroll to finish the form)
* Please do not put brackets or +1
What services are you looking for?

Choose as many as apply. Select at least one.

Thank you! Your submission has been received!
Close